
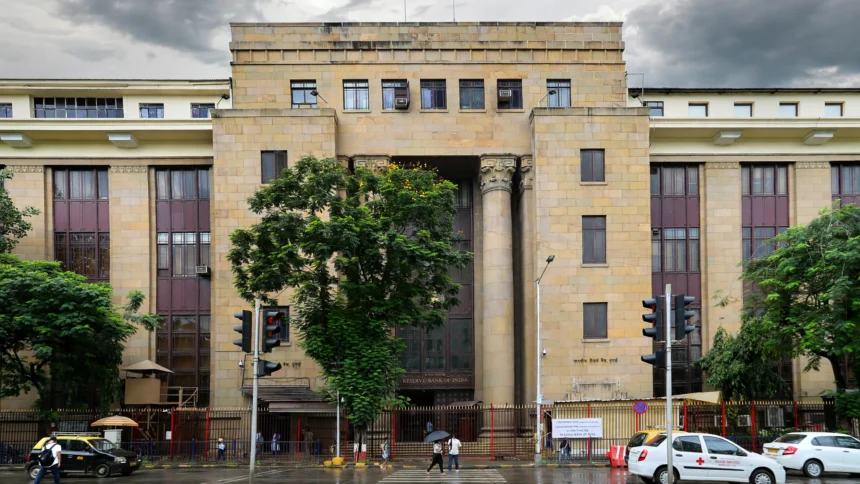
Millions of small borrowers in India could soon find it easier to qualify for a microfinance loan. The Reserve Bank of India has said it may review the Rs 3 lakh annual household income limit that decides who counts as a microfinance borrower, a ceiling the industry has long called outdated. The signal came from Deputy Governor Shirish Chandra Murmu at a Microfinance Institutions Network (MFIN) event in Mumbai, reported on Sunday, November 15.
Murmu stopped well short of promising a higher limit. He said a review would depend on the central bank’s assessment of the need for a revision and on developments in the industry. But even a review matters, because the Rs 3 lakh threshold has not kept pace with rising rural incomes and inflation, and lenders say it now shuts out households that still depend on small-ticket credit.
What the Rs 3 lakh limit means today
Under the RBI’s microfinance framework, a household qualifies for a microfinance loan only if its annual income is up to Rs 3 lakh. The limit is meant to keep microfinance focused on low-income borrowers, the segment formal banks have traditionally served poorly. Lenders argue, however, that incomes have moved on since the threshold was set, and families with modest income growth now sit above the line even though their borrowing needs have not changed.
Murmu acknowledged the case for a fresh look, but he attached a clear condition. Any change must be matched by stronger household income assessment and reporting by microfinance institutions, he said, so the relaxation cannot be misused. The sector’s credibility, he stressed, depends on lenders knowing borrowers’ real incomes rather than relying on rough estimates.
The 50 percent repayment cap stays put
While the income limit may be revisited, the other big number in microfinance regulation is not up for debate. The industry had asked the RBI to soften the 50 percent cap on a household’s monthly loan repayment to income ratio, known as the fixed obligation to income ratio (FOIR), by excluding the principal component of certain loans. Murmu said no.
Such an exclusion would defeat the purpose of the limit, he said, and would understate how much debt a household is really carrying. The 50 percent cap exists to stop borrowers sliding into over-indebtedness while leaving a reasonable share of income free for food, schooling, health care and other essentials. Murmu called the cap already a liberal limit, given the thin financial cushion most low-income households have.
What else the RBI flagged
Murmu’s remarks went beyond the two limits. He pointed out that microloan interest rates have moved up across all categories of regulated lenders, and said competition must translate into fair and competitive lending rates for borrowers, not just market share for lenders.
He also warned that prolonged geopolitical strains and extreme weather hit low-income households hardest. A rainfall shortfall has already led several states to declare drought, squeezing farm incomes where microfinance lending is heaviest. For lenders, the message was plain: tighten practices now, because their borrowers have the least room to absorb a shock.
What happens next
No timeline has been given for the review, and no new threshold has been suggested. The RBI will first assess whether a revision is needed and how the industry is behaving, which means lenders’ own income reporting standards could decide how far the limit moves.
For borrowers, the practical meaning is limited for now. The Rs 3 lakh ceiling still applies, and the 50 percent repayment cap is firmly in place. But the door to a higher income limit is open, and the industry will watch the RBI’s next move closely. If the review leads to a raise, households earning just above Rs 3 lakh a year could regain access to regulated small loans instead of turning to informal moneylenders.
Frequently asked questions
What is the current income limit for microfinance borrowers?
Households with an annual income of up to Rs 3 lakh qualify as microfinance borrowers under the RBI framework. The RBI has now said it may review this limit.
Will the Rs 3 lakh limit definitely be raised?
No. Deputy Governor S C Murmu said a review would depend on the RBI’s assessment of the need for a revision and on developments in the industry. No new figure or timeline has been announced.
What is the 50 percent FOIR cap?
It caps a household’s total monthly loan repayments at 50 percent of its monthly income, so that at least half the income stays available for essential spending. The RBI has refused to dilute it.
Why does the industry want the income limit raised?
Lenders say rising rural incomes and inflation have made the Rs 3 lakh ceiling outdated, and it now excludes households that still need small-ticket credit.
When will the review conclude?
The RBI has not given a timeline. The review will follow its assessment of the sector, including how well lenders verify and report borrower incomes.
The RBI’s next word on microfinance norms will show whether the review turns into a real change. Until then, the Rs 3 lakh ceiling and the 50 percent cap both remain in force.