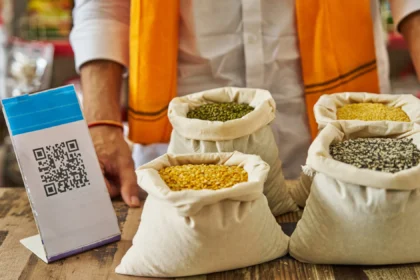


If you run a shop, a restaurant, or an online store that accepts UPI, this week could bring a small but meaningful relief. The National Payments Corporation of India is expected to announce a postponement of the proposed merchant discount rate (MDR) on UPI transactions, pushing the rollout from October 15, 2026 to January 1, 2027.
- What the proposed UPI MDR actually is
- Why retailers pushed back
- What the delay means for fintech stocks
- What it means for you
- The bigger picture
- FAQs
- Will I be charged for using UPI?
- Which UPI payments would attract MDR?
- When will UPI MDR start?
- Are small shops exempt from UPI MDR?
- Why did fintech stocks fall and rise on the news?
The buzz around the delay picked up after the NPCI-led UPI and Services Steering Committee met to discuss the timing of the fee and the pushback it has received from retail traders and fintech companies. A formal decision is expected shortly, and sources indicate the committee is leaning towards giving merchants more breathing room before the festive season hits full swing.
What the proposed UPI MDR actually is
MDR is the fee merchants pay to banks and payment companies for processing a digital transaction. For years, UPI has been free for merchants, which is a big part of why it became India’s default way to pay. That may soon change, but not for everyone and not for every payment.
Here is what the proposed framework looks like:
- A 0.4 per cent MDR would apply to merchant transactions above Rs 2,000, capped at Rs 300 per transaction.
- At that rate, a Rs 10,000 payment would cost the merchant Rs 40.
- Certain categories, including bill payments, utilities, education and fuel, would attract a flat Rs 5 fee per transaction above Rs 2,000.
- Consumers would not be charged the fee. It falls on the merchant.
- Small businesses are expected to be shielded. Authorities are considering exempting firms with annual turnover of up to Rs 40 lakh.
Why retailers pushed back
The original October 15 start date landed right in the middle of India’s festive shopping season, the period when merchants make a large share of their annual revenue. Retail trade associations argued that adding a transaction cost during Diwali and the year-end rush would squeeze margins that are already thin.
The protest went beyond letters. Trader bodies had planned a nationwide “No UPI Day” on October 2 to register their opposition, but withdrew the call after a meeting with Union Finance Minister Nirmala Sitharaman. The finance minister has since indicated that stakeholders in the payments ecosystem would decide the timing of the rollout.
The steering committee has also been asked to clarify which transactions the fee covers and how the split works between acquiring banks, issuing banks and third-party app providers. For many small merchants, that confusion alone was reason to ask for more time.
What the delay means for fintech stocks
The uncertainty has already whipsawed listed fintech companies. When the postponement talk first surfaced, shares of One 97 Communications, the parent of Paytm, tumbled about 10 per cent in early trade, with Mobikwik, Pine Labs and others sliding too. Fintech firms had rallied when the fee was first announced, since MDR revenue would flow partly to them.
Last week the mood flipped again. Paytm and Mobikwik shares rose sharply in early trading as investors awaited the committee’s decision, with Mobikwik climbing as much as 8 per cent. The swing shows how much is riding on one announcement: the MDR framework would hand payment companies a brand-new revenue stream on eligible UPI transactions, and Paytm alone gets roughly 85 per cent of its gross merchandise value from person-to-merchant UPI payments.
What it means for you
If you are a customer, nothing changes. Your UPI payments stay free either way; the fee is charged to merchants, not payers. But there is an indirect catch worth watching: some retailers have warned they might pass on higher processing costs through prices, which is one reason the government is cautious about the festive season.
If you are a merchant, a delay to January gives you two things: a cost-free festive quarter, and time to understand the new rules before they apply. The likely exemption for businesses with annual turnover up to Rs 40 lakh would take a large share of neighbourhood shops out of the fee’s scope entirely.
The bigger picture
UPI now processes billions of transactions every month, and the question of who pays for that infrastructure has been building for years. Banks and payment apps have argued that a zero-fee model is not sustainable forever. Merchants and consumer groups counter that UPI’s whole success came from being free and frictionless.
The RBI’s own view has been measured. Governor Sanjay Malhotra has said a small MDR fee is unlikely to dent UPI volumes, suggesting the central bank does not see the charge as a threat to digital payments. The fight, then, is about timing and fairness, not the principle.
For now, all eyes are on the NPCI’s announcement. A postponement to January 1, 2027 would keep UPI free through Diwali, the wedding season and Christmas, and push the real test of merchant tolerance into the new year. Watch this space.
FAQs
Will I be charged for using UPI?
No. The proposed MDR is paid by merchants, not consumers. Your UPI payments remain free.
Which UPI payments would attract MDR?
The proposed 0.4 per cent fee applies to merchant transactions above Rs 2,000, capped at Rs 300. Small everyday payments below Rs 2,000 are unaffected.
When will UPI MDR start?
It was originally scheduled for October 15, 2026, but the NPCI is expected to postpone the rollout to January 1, 2027.
Are small shops exempt from UPI MDR?
Under consideration: businesses with annual turnover of up to Rs 40 lakh may be exempted from the fee.
Why did fintech stocks fall and rise on the news?
Payment companies like Paytm would earn a share of MDR revenue, so any delay to the rollout pushes their expected income further out, which moved their share prices.
Published on October 12, 2026. This is a developing story; we will update it as the NPCI’s decision is announced.